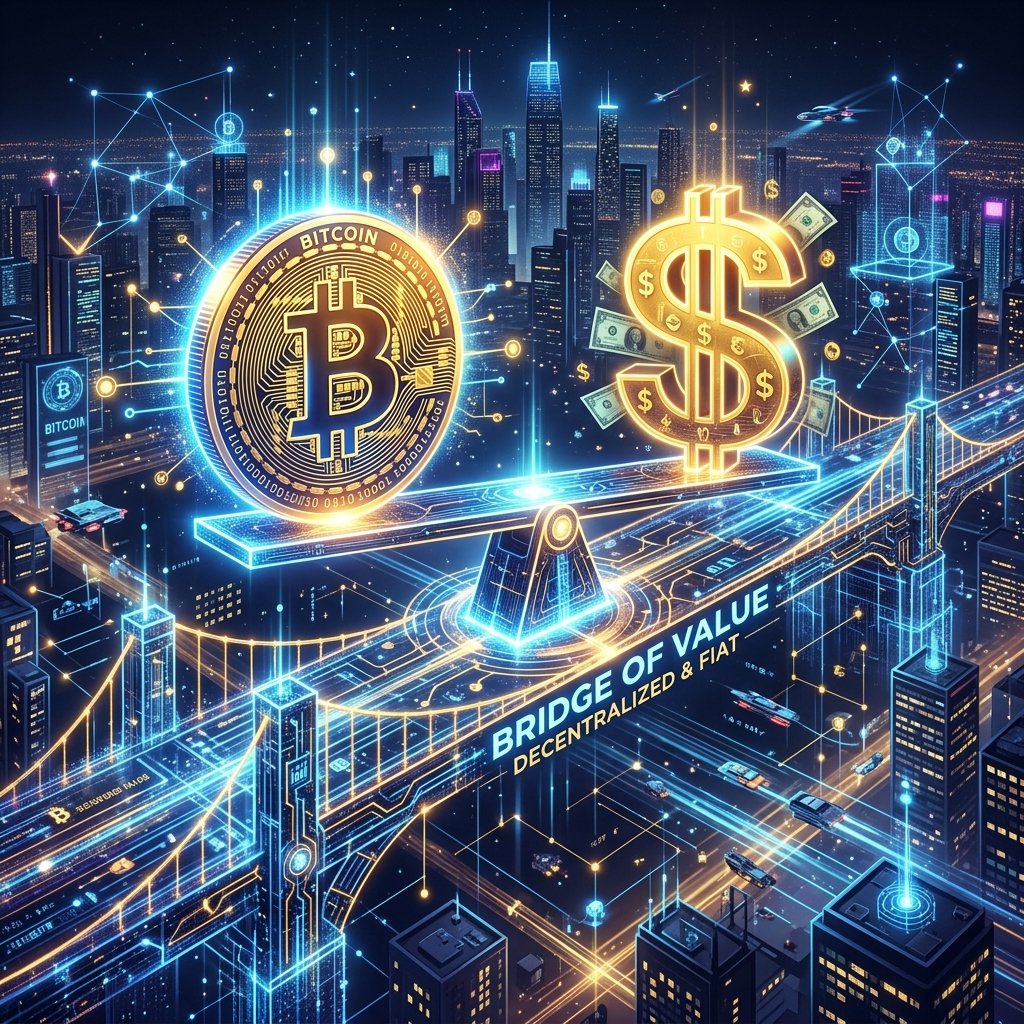
For many observing from the outside, the cryptocurrency market is synonymous with extreme price volatility. While this volatility presents opportunities for significant returns, it also renders traditional cryptocurrencies like Bitcoin and Ethereum impractical for everyday use as a medium of exchange or a reliable unit of account. This is where stablecoins enter the equation. Having stablecoins explained is crucial for understanding the foundational plumbing of the decentralized economy. A stablecoin is a type of cryptocurrency designed to maintain a stable value relative to a specific asset, most commonly the US Dollar. By combining the stability of traditional fiat currencies with the speed, borderless nature, and programmability of blockchain technology, stablecoins have become the indispensable bridge between traditional finance (TradFi) and decentralized finance (DeFi).
Fiat-Collateralized Stablecoins
The most common and widely understood model is the fiat-collateralized stablecoin. In this structure, the issuing entity holds a reserve of fiat currency—such as US dollars in a bank account—that is equivalent to the number of stablecoins in circulation. For every token minted, a corresponding dollar must be deposited; conversely, when a token is redeemed, the dollar is paid out, and the token is burned. Tether (USDT) and USD Coin (USDC) are the prime examples of this model. Their primary advantage is price stability and straightforward mechanics. However, they rely heavily on centralized entities to manage the reserves and require regular, transparent audits to ensure that the stablecoins are fully backed 1:1, mitigating counterparty risk.
Crypto-Collateralized Stablecoins
To circumvent the reliance on centralized entities and traditional banking infrastructure, the crypto ecosystem developed crypto-collateralized stablecoins. These stablecoins maintain their peg through smart contracts and over-collateralization using other cryptocurrencies. The most prominent example is MakerDAO’s DAI. Users deposit volatile assets like Ethereum into a smart contract as collateral to generate DAI. Because the collateral is volatile, users must deposit significantly more value than the DAI they mint (e.g., depositing $150 worth of ETH to generate 100 DAI). If the value of the collateral drops below a certain threshold, the smart contract automatically liquidates it to ensure the system remains solvent. This model offers high decentralization and transparency but introduces complex mechanics and vulnerability to extreme, sudden market crashes.
Algorithmic Stablecoins: The High-Risk Frontier
The most experimental and controversial category is algorithmic stablecoins. These tokens attempt to maintain their peg not by holding reserves of collateral, but rather through complex algorithms and smart contracts that automatically expand or contract the token supply based on market demand—much like a central bank operates. They often utilize a dual-token system involving the stablecoin and a secondary ‘seigniorage’ token to absorb volatility. While theoretically elegant and highly scalable because they are capital efficient (requiring no collateral), history has shown them to be extremely fragile. The infamous collapse of the TerraUSD (UST) algorithmic stablecoin in 2022 highlighted the catastrophic risks associated with this model, leading to heightened regulatory scrutiny over this specific asset class.
The Crucial Role of Stablecoins in DeFi
Safe Haven: Traders use stablecoins to secure profits and protect their capital during periods of high market volatility without having to cash out to fiat currency.
Trading Pairs: They serve as the primary quote currency on major exchanges (both centralized and decentralized), providing deep liquidity for nearly all trading pairs.
Lending and Borrowing: In DeFi protocols, stablecoins are the most heavily utilized assets for lending and borrowing, offering users predictable interest rates without the risk of principal depreciation.
Regulatory Scrutiny and Future Outlook
Due to their immense growth and potential systemic importance, stablecoins are currently the primary focus of financial regulators worldwide. Concerns center around the transparency of reserves held by centralized issuers, the potential for ‘bank runs’ if reserves are deemed insufficient, and the impact of algorithmic models on market stability. Regulations such as the EU’s MiCA framework place strict capital and reporting requirements on stablecoin issuers. Furthermore, the development of Central Bank Digital Currencies (CBDCs) introduces a potential sovereign competitor to privately issued stablecoins. The future landscape will likely be shaped by stringent compliance standards, ensuring that stablecoins can safely fulfill their role as the settlement layer for the digital economy.
Frequently Asked Questions (FAQ)
How do stablecoins stay at exactly $1.00?
Fiat-backed stablecoins stay at $1 through arbitrage. If the token trades at $0.99, traders buy it and redeem it with the issuer for $1.00 of the reserve fiat, profiting from the difference and pushing the price back up. If it trades at $1.01, they deposit $1.00, mint a token, and sell it, pushing the price down.
Are stablecoins completely risk-free?
No. Fiat-backed stablecoins carry counterparty risk (the issuer might mismanage reserves or face regulatory action). Crypto-backed stablecoins face liquidation risks if the collateral crashes. Algorithmic stablecoins carry systemic risks of complete collapse (‘death spirals’).
Can stablecoins be used for everyday purchases?
Yes, and this use case is growing. Many payment processors and crypto debit cards allow users to spend stablecoins just like traditional currency, bypassing the volatility associated with assets like Bitcoin.
Conclusion
In summary, having stablecoins explained clarifies their position as the bedrock of the modern cryptocurrency ecosystem. By providing a stable unit of account and a reliable medium of exchange on-chain, they enable the complex financial operations of DeFi and provide a crucial safe haven for traders. While different mechanisms—fiat-collateralized, crypto-collateralized, and algorithmic—offer varying degrees of decentralization and capital efficiency, they all aim to solve the fundamental problem of crypto volatility. As regulatory frameworks crystallize to ensure consumer protection and systemic stability, stablecoins are poised to become an even more integral component of global finance, potentially bridging the gap between traditional banking and the decentralized future.
 DeFi